Oil and Gas Capex Outlook Points to Quiet but Durable Valve Demand
Operators are holding capital discipline into 2027, which means fewer megaprojects but a deep, steady stream of maintenance and brownfield valve work.
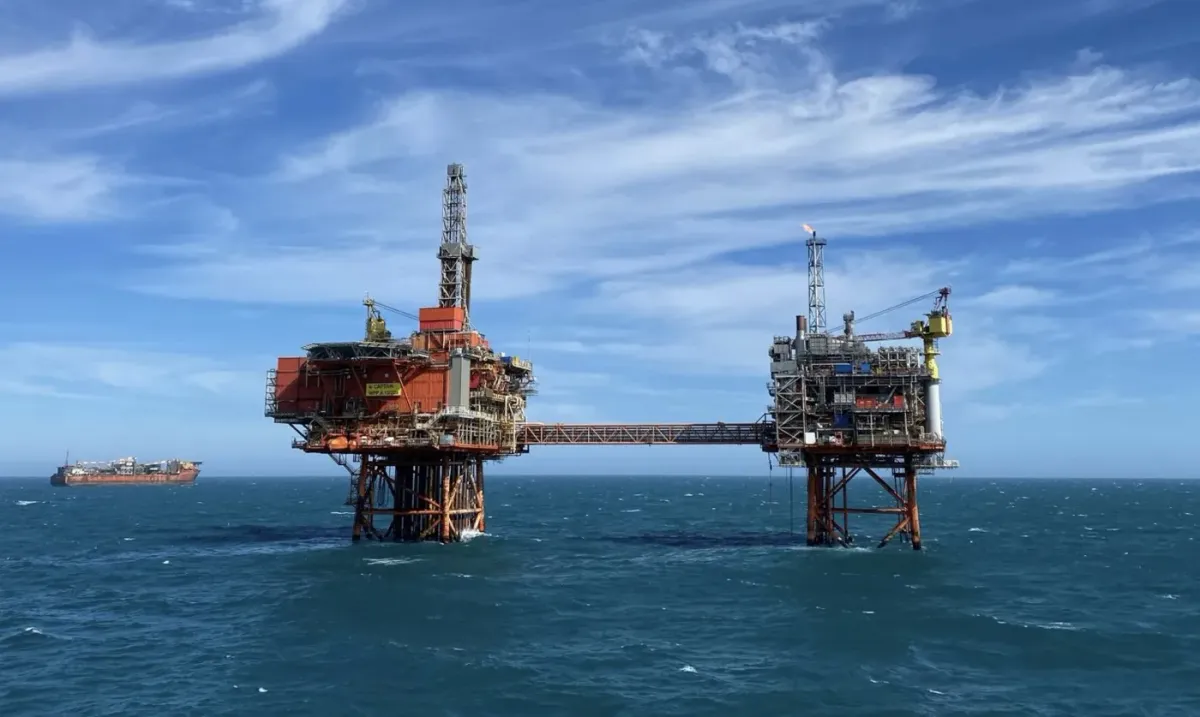
The 2027 capital spending outlook for the international oil and gas sector describes a market that has settled into discipline. Upstream operators are prioritizing returns over volume, National Oil Companies in the Gulf continue their strategic expansions, and service companies are positioning for a maintenance-heavy, megaproject-light cycle.
What capex discipline means for valves
A disciplined market is not a dead market — it redistributes demand. New offshore greenfield projects with thousands of valves per development are fewer. In their place, brownfield work expands: debottlenecking, emissions-reduction retrofits, flare-gas recovery and digital instrumentation upgrades all consume valves in the hundreds rather than thousands per project, but continuously.
Aftermarket is the quiet winner. Aging facilities need replacement valves on rolling schedules, and inventory-management service contracts — where the supplier owns stocking responsibility — are growing as operators shrink internal procurement overhead.
Positioning for the cycle
- Megaproject valve awards are fewer; brownfield work is continuous
- Emissions-reduction retrofits are a growing brownfield valve category
- Inventory service contracts are replacing transactional purchasing at mature sites
Manufacturers read the same forecast and reach different conclusions. Those built for large project volume are chasing the remaining LNG and Gulf expansion work; those built for flexibility are leaning into aftermarket contracts. Both strategies are rational — but they require very different supply chains.
Segment breakdown
The demand picture splits cleanly by segment. Upstream greenfield is the weakest, with only sanctioned deepwater and Gulf expansions generating project-scale valve packages. Gas value chains dominate growth: LNG, gas processing and transmission all carry high valve content and firm schedules. Downstream is steady-but-shrinking, with closures offset by modernization at surviving refineries. Midstream benefits from emissions-compliance work — leak detection and repair programs, vapor recovery, flare reduction — each consuming valves in steady maintenance volumes. For suppliers, segment mix is now the decisive strategic variable: a portfolio weighted toward gas infrastructure and aftermarket faces a fundamentally better cycle than one anchored in conventional refining.
Aftermarket strategy
Aftermarket growth is changing how suppliers organize. Inventory service contracts — where the supplier forecasts, stocks and replenishes valve spares at the operator's sites — are expanding because they cut the operator's working capital and the supplier's sales cost simultaneously. Repair and recertification volume grows with facility age, pulling valve makers into service businesses their predecessors avoided. Digital channels support the shift: spare-part identification, once a drawing-room archaeology project, increasingly runs through online platforms that match installed valves to current equivalents. The manufacturers thriving in this cycle treat aftermarket not as a residual but as a designed business, with its own products, pricing and logistics.



